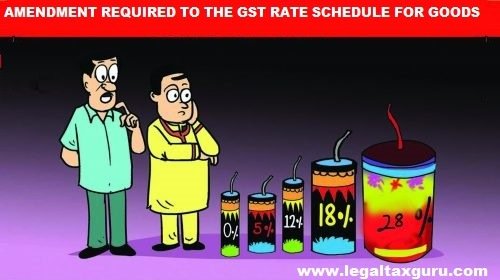
Amendment Required to the GST Rate Schedule For Goods

I. The following amendments or additions are required to be made to the aforesaid document:...

SPECIALIZED LEGAL DATABASE SPECIALIZED LEGAL DATABASE

Taxmann Direct Tax & Corporate Governance Research Suite 2026

Real-time ITAT, NCLT tribunal judgments, statutory MCA circulars, and comprehensive commentaries for CAs and Advocates.

rate-of-gst-e1478519321605 - Copy

I. The following amendments or additions are required to be made to the aforesaid document:

1.In S.No.22,-

(a) In the Nil rate column, the entry “Tender coconut water put in unit container and
carry a registered brand name [2202 90 90]”, may be read as:

“Tender coconut water other than put in unit container and carry a registered brand
name [2202 90 90]”.

(b)  In 12% rate column, in the entry “Fruit pulp or fruit juice based drinks [22029030]”,
tariff item 2202 90 30 may be read as 2202 90 20.

AUTHORITATIVE LEGAL REPOSITORY AUTHORITATIVE LEGAL REPOSITORY

SCC Online Supreme Court & High Court Comprehensive Archive

Over 1.2 million verified judicial precedents with true-print PDFs, cited judgment cross-references, and digest notes.

2.  In S.No.85, in the 28% rate column, the entry “Electrical machines and
equipment 
having individual functions, not specified or included elsewhere in this chapter

[8543]” may be omitted.“8543 Electrical machines and apparatus having individual 

functions, not specified or included elsewhere in this
chapter” is already covered in
 
the 18% rate column.

3. In the footnote below the Table which gives the list of goods for which the GST rates are yet to be decided by the GST Council, the following entries may be added:

(i) Cereals and flour put up in unit container and bearing a registered brand name.

(ii) Puja samagri including havan samagri will be under Nil category. However,
 
the exact formulation for the same is yet to be finalised.
PRACTITIONER HANDBOOK PRACTITIONER HANDBOOK

Master Handbook on GST Input Tax Credit & Appellate Litigation

Comprehensive statutory handbook with ready reckoners, clause-by-clause analysis, and tribunal precedents. Available in Print + Digital Edition.

Practitioner Discussion & Analysis

Contribute your legal commentary or cite relevant tribunal precedents
⚖️ Submissions are moderated according to Legal Tax Guru Editorial Guidelines.

Stay Ahead of Tax & Legal Developments

Join 45,000+ Advocates, Chartered Accountants, and Corporate Counsels receiving daily statutory notifications & judicial commentaries.

TRUSTED REPOSITORY

Trusted Legal & Tax Resources

Authoritative citations, handbooks & statutory publications referenced across Indian Courts & Tribunals