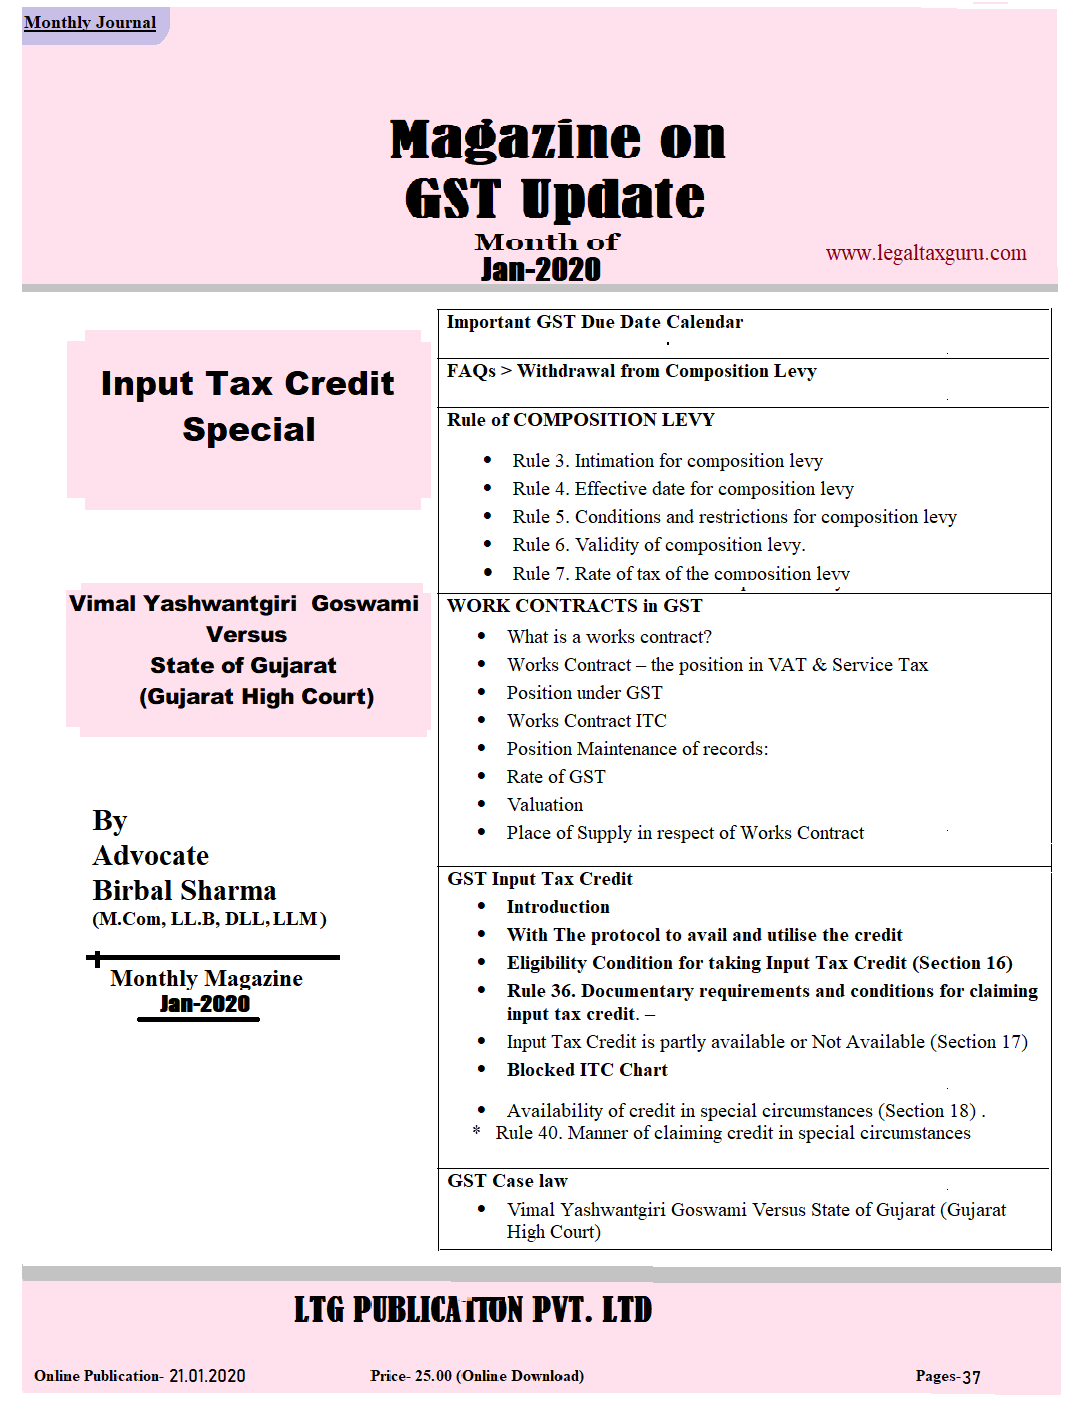
GST Magazine Update Month of Jan-2020 (Digital) || Input Tax Credit Special
You are viewing the sample preview & table of contents. The complete downloadable PDF unlocks instantly upon payment.
Online Edition :21.01.2020
Pages -37
Price - 25
Click
📋 Key Publication Details
GST Magazine Update Month of Jan-2020 || Input Tax Credit Special
Online Edition :21.01.2020 Pages -37 Price - 25 Click Below link for buy [purchase_link id="85205" text="Purchase" style="button" color="dark-gray"]
| Sr.No | CONTENTS | Page No. |
| 1. | Important GST Due Date Calendar | 4-5 |
| 2. | FAQs > Withdrawal from Composition Levy | 6-8 |
| 3. |
Rule of COMPOSITION LEVY• Rule 3. Intimation for composition levy • Rule 4. Effective date for composition levy • Rule 5. Conditions and restrictions for composition levy • Rule 6. Validity of composition levy. • Rule 7. Rate of tax of the composition levy |
9-12 |
| 4. |
WORK CONTRACTS in GST• What is a works contract? • Works Contract – the position in VAT & Service Tax • Position under GST • Works Contract ITC • Position Maintenance of records: • Rate of GST • Valuation • Place of Supply in respect of Works Contract |
13-19 |
5. |
GST Input Tax Credit• Introduction • With The protocol to avail and utilise the credit • Eligibility Condition for taking Input Tax Credit (Section 16) • Basic Condition (Section 16 (1): - • Conditions of Taking Input Tax Credit to registered person (Section 16 (2- • Delivery by goods in lot or installment • Reverse Input Tax Credit, the amount towards the value of supply along with tax note paid within a period of 180 days •“Rule 37. Reversal of input tax credit in the case of non-payment of consideration. - • No Input Tax Credit if depreciation is Claimed on tax component (Section 16(3) • Time limit of claim Input Tax Credit (Section 16 (4) • Rule 36. Documentary requirements and conditions for claiming input tax credit. – • Rule 36. Documentary requirements and conditions for claiming input tax credit.- • Rule 36 (2) Particulars to be contained in documents • Rule 36 (3) No ITC on demand paid on account of fraud •Input Tax Credit is partly available or Not Available (Section 17) • Section 17. (1) goods or services or both are used by the registered person partly for the purpose of any business and partly for other purposes • Section 17 (2) goods or services or both are used by the registered person partly for effecting taxable supplies including zero-rated supplies • Section 17 (3) What supplies are included in exempt supply • Section 17 (4) Input Tax Credit in case banking company or a financial institution • Section 17 (5) Input Tax Credit shall not be available on certain goods/services • Blocked ITC Chart • Availability of credit in special circumstances (Section 18) . • More than One year (expiry) of the date of issue of tax invoice not eligible for credit • Sale of capital goods or plant and machinery after taking input tax credit •Rule 40. Manner of claiming credit in special circumstances |
20-34 |
6. |
GST Case law• Vimal Yashwantgiri Goswami Versus State of Gujarat (Gujarat High Court) |
35-37 |
About This Publication
GST Magazine Update Month of Jan-2020 (Digital) || Input Tax Credit Special provides comprehensive judicial commentaries, High Court and Supreme Court landmark rulings, CBIC/CBDT notifications, and direct practical guidance for Tax Advocates, Chartered Accountants, and Corporate Counsel.
Key Highlights & Practice Areas Covered
- Detailed GST Due Date Calendar and compliance checklists for timely return filings.
- Analysis of high-stake judicial pronouncements by High Courts & Appellate Authorities for Advance Ruling (AAR).
- Section-wise commentaries on statutory amendments, Input Tax Credit (ITC) restrictions, and penalty mitigation.
- Corporate fraud defense, PMLA jurisprudence, and prosecution provisions under direct & indirect tax statutes.
Editorial Advisory Board
Compiled and vetted by senior tax litigators and chartered tax advisors at Legal Tax Guru Press. For editorial queries, corrections, or manuscript contributions, reach out to editorial@legaltaxguru.com.
Annual Magazine Subscription Plans
Get uninterrupted monthly editions delivered directly to your doorstep and digital inbox.
- ✓ 12 Monthly Digital & Print Issues
- ✓ Supreme Court & High Court Digest
- ✓ Free Delivery across India
- ✓ WhatsApp Immediate Access
- ✓ 24 Monthly Digital & Print Issues
- ✓ Case Law Search Companion
- ✓ Priority Desk & Webinar Invites
- ✓ Save ₹500 over annual rates
Direct Bank Transfer Details
After making payment, please WhatsApp your receipt/screenshot to 8854082822 or email legaltaxguru@gmail.com.
Complete PDF Edition Unlocks Upon Payment
Without payment, only the online sample preview and chapter table of contents are visible. Once you complete the purchase, the full unabridged digital publication (PDF) becomes immediately available for instant download.